I’m doing something different today from just updating ranged forecasts. Over the weekend, I explored shifting from strictly return oriented forecasts to return over risk ratios. The daily return model is fundamentally unchanged. I’m just now also modeling for downside risk based on actual return when the forecast and actual results were in opposite directions. The risk result is floored at a value meaningfully above 0 to prevent electing to go after a puny anticipated rate of return just because we’re projecting a very puny rate of downside risk.
Investing based on the resulting ratio rather than daily return can theoretically filter out higher risk exposures to the market. In back testing, the number of days in the market go down by 24% and the number of days utilizing leverage when willing to entertain leverage go down by 29%.
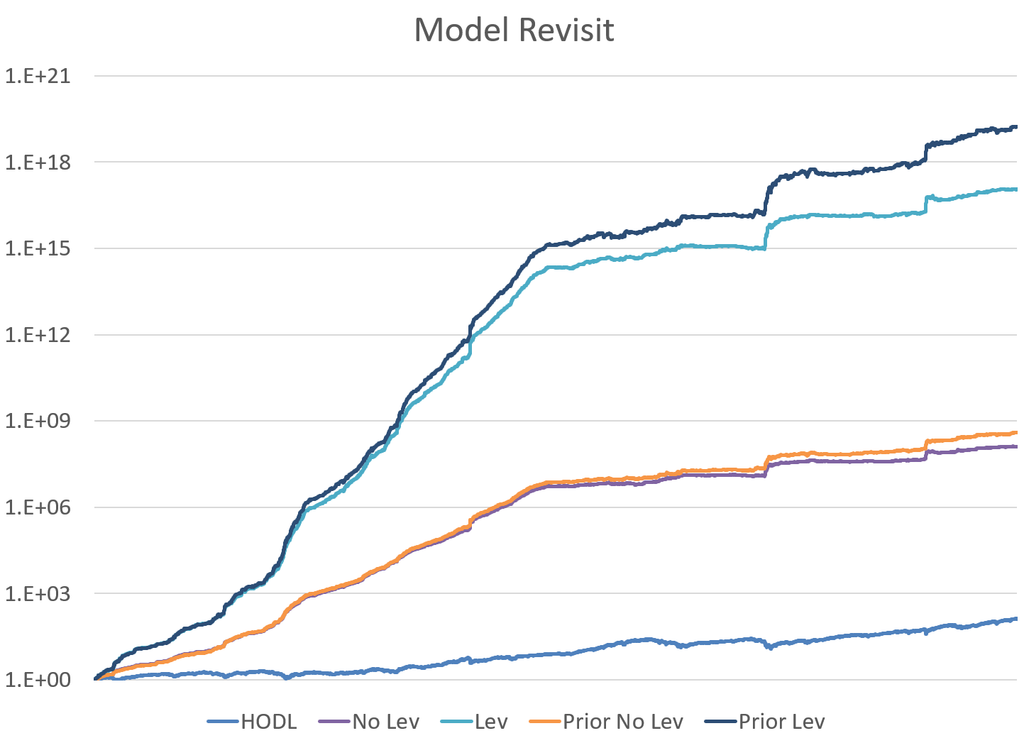
The change in strategy theoretically reduces model return slightly, but risk is down considerably more sharply. Here are the Daily Sharpe Ratios (Reward/Risk) metrics for backtesting each of the graphed lines:
Sharpe Ratios for Strategies
Hold on for Dear Life (Buy and hold index): .02853
No Lev: .1718
Lev: .1751
Prior No Lev: .1565
Prior Lev: .1453
Shifting to the new algorithm will be safer regarding volatility while theoretically only sacrificing modest returns.